
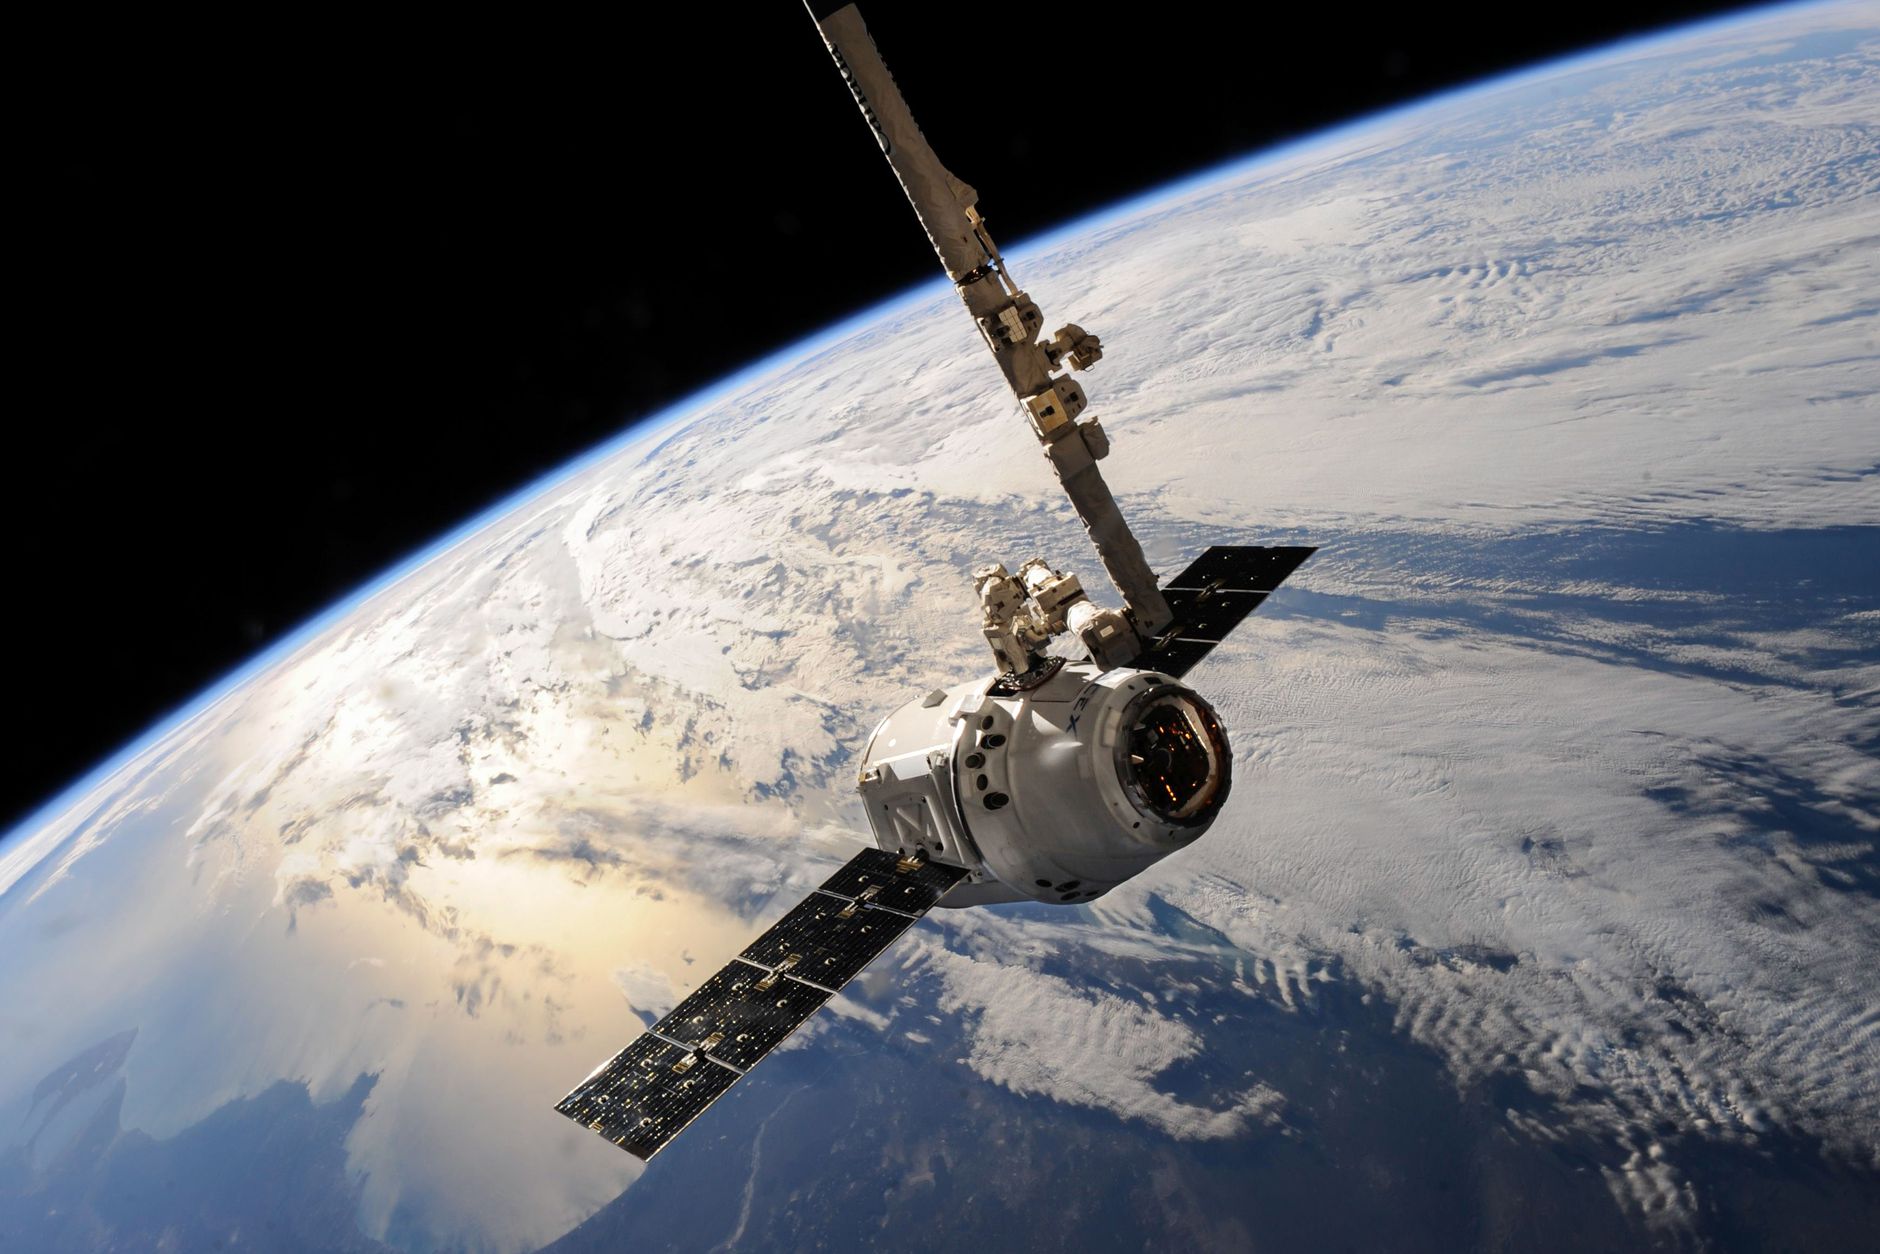
Photo by SpaceX on Pexels
The Satellite Disruptor Has Arrived — and Telecoms Are Taking Notice
For years, satellite internet was easy to dismiss. High latency, eye-watering costs, and limited capacity made it a last-resort option for the truly underserved. Then SpaceX launched Starlink, and the conversation changed entirely. Today, with more than 6,000 low Earth orbit (LEO) satellites in service and over 3 million active subscribers across more than 100 countries, Starlink has transformed from a curiosity into a credible competitive force that terrestrial network operators can no longer afford to ignore.
The core question facing the telecom industry is not whether Starlink will replace fiber or 5G — it won’t, at least not in any near-term scenario. The real question is subtler and, in many ways, more dangerous for incumbents: how much of the customer relationship is Starlink prepared to claim, and what does that mean for the long-term economics of traditional operators?
Understanding the Technical Battlefield
Starlink’s Gen2 satellites, operating in low Earth orbit at altitudes between 340 and 570 kilometers, deliver latency figures in the 20–60ms range — a staggering improvement over legacy geostationary systems that sat at 600ms or more. Throughput for residential users regularly hits 100–200 Mbps downstream, with premium tiers like Starlink Business offering up to 500 Mbps. The recently launched Starlink Direct to Cell service, which leverages eNodeB technology embedded directly into satellites, enables LTE connectivity to standard smartphones without any specialized hardware.
This last development is particularly significant. By partnering with carriers such as T-Mobile in the United States, Optus in Australia, and Rogers in Canada, Starlink is threading itself into the existing mobile ecosystem rather than fighting against it — a strategy that simultaneously makes it a partner and a potential long-term competitor to those very same operators.
Where the Real Threat Lives: The Network Edge and Underserved Markets
The fiercest competitive battleground is not in dense urban cores where fiber and 5G reign supreme. It is at the network edge — rural communities, suburban fringe areas, maritime routes, aviation corridors, and enterprise campuses where terrestrial infrastructure is thin, expensive to maintain, or simply absent. These are precisely the markets where Starlink has planted its flag most aggressively.
Fixed wireless access (FWA) providers and rural telephone cooperatives are feeling the pressure most acutely. In regions where a local ISP might charge $80–$120 per month for 25–50 Mbps service over aging DSL infrastructure, Starlink’s residential plan at around $120 per month for dramatically superior speeds represents a compelling alternative. Customer churn in these markets is rising, and the trend line is not flattering for legacy providers.
Enterprises operating remote facilities — oil and gas installations, mining operations, agricultural enterprises — represent another high-value segment being actively courted by Starlink’s business and priority tiers. These are customers that mobile network operators have historically served with costly private APN arrangements and managed connectivity solutions. Starlink’s flat-rate, high-throughput offerings are undercutting those propositions rapidly.
The Incumbent Response: Hybrid Networks and Strategic Partnerships
Smart operators are not waiting passively. Several major telecoms have begun incorporating LEO satellite capacity into their own portfolio strategies, effectively adopting a hybrid network model. Viasat, OneWeb (now Eutelsat OneWeb), and Amazon’s Project Kuiper are all positioning as wholesale partners for carriers that want satellite reach without ceding the customer relationship to SpaceX. Telecom operators including SoftBank, BT Group, and Deutsche Telekom have explored or entered commercial agreements with LEO providers to extend their service footprint without the capital expenditure of terrestrial buildout.
The logic is sound: if satellite capacity is inevitable, better to integrate it as a managed layer within your own service stack than to let a third party own the customer touchpoint. Bundling satellite backhaul into a unified connectivity product — one bill, one app, one support contact — preserves the operator’s position as the primary relationship holder.
The Customer Relationship: Who Owns the Last Mile of Trust?
This is where the strategic stakes become existential. Telecom operators have long understood that whoever controls the last mile controls the customer. Starlink, with its sleek self-install hardware, intuitive app, and direct billing relationship, is quietly building its own last-mile brand equity — even in markets where a terrestrial operator technically provides the dominant connection.
As Starlink expands into mobility services, in-flight connectivity, and maritime broadband, its addressable market grows far beyond rural residential. Each new vertical it enters represents a potential erosion of revenue streams that traditional operators have historically taken for granted.
Industry Outlook: Coexistence, Competition, and the Long Game
The consensus among analysts is that the near-term future is one of coexistence rather than outright replacement. Terrestrial networks — particularly dense 5G deployments and fiber-to-the-premises — retain decisive advantages in capacity, latency consistency, and cost-per-bit at scale. A single mid-band 5G small cell can serve hundreds of simultaneous users with multi-gigabit aggregate throughput that no satellite constellation can economically match in urban environments today.
But “coexistence” should not lull operators into complacency. Starlink is a well-capitalized, innovation-driven competitor with a vertically integrated hardware and software stack, a growing spectrum portfolio, and a parent company in SpaceX with a long-term vision measured in decades, not quarterly earnings cycles.
For telecoms, the path forward demands honest assessment of where their network edges are weakest, where customer satisfaction is lowest, and where Starlink’s value proposition is most compelling. Those gaps need to be closed — whether through accelerated infrastructure investment, strategic satellite partnerships, or aggressively differentiated service bundles. The battle for the edge of the network is, ultimately, a battle for the heart of the customer. And that is a contest no operator can afford to lose on autopilot.
