
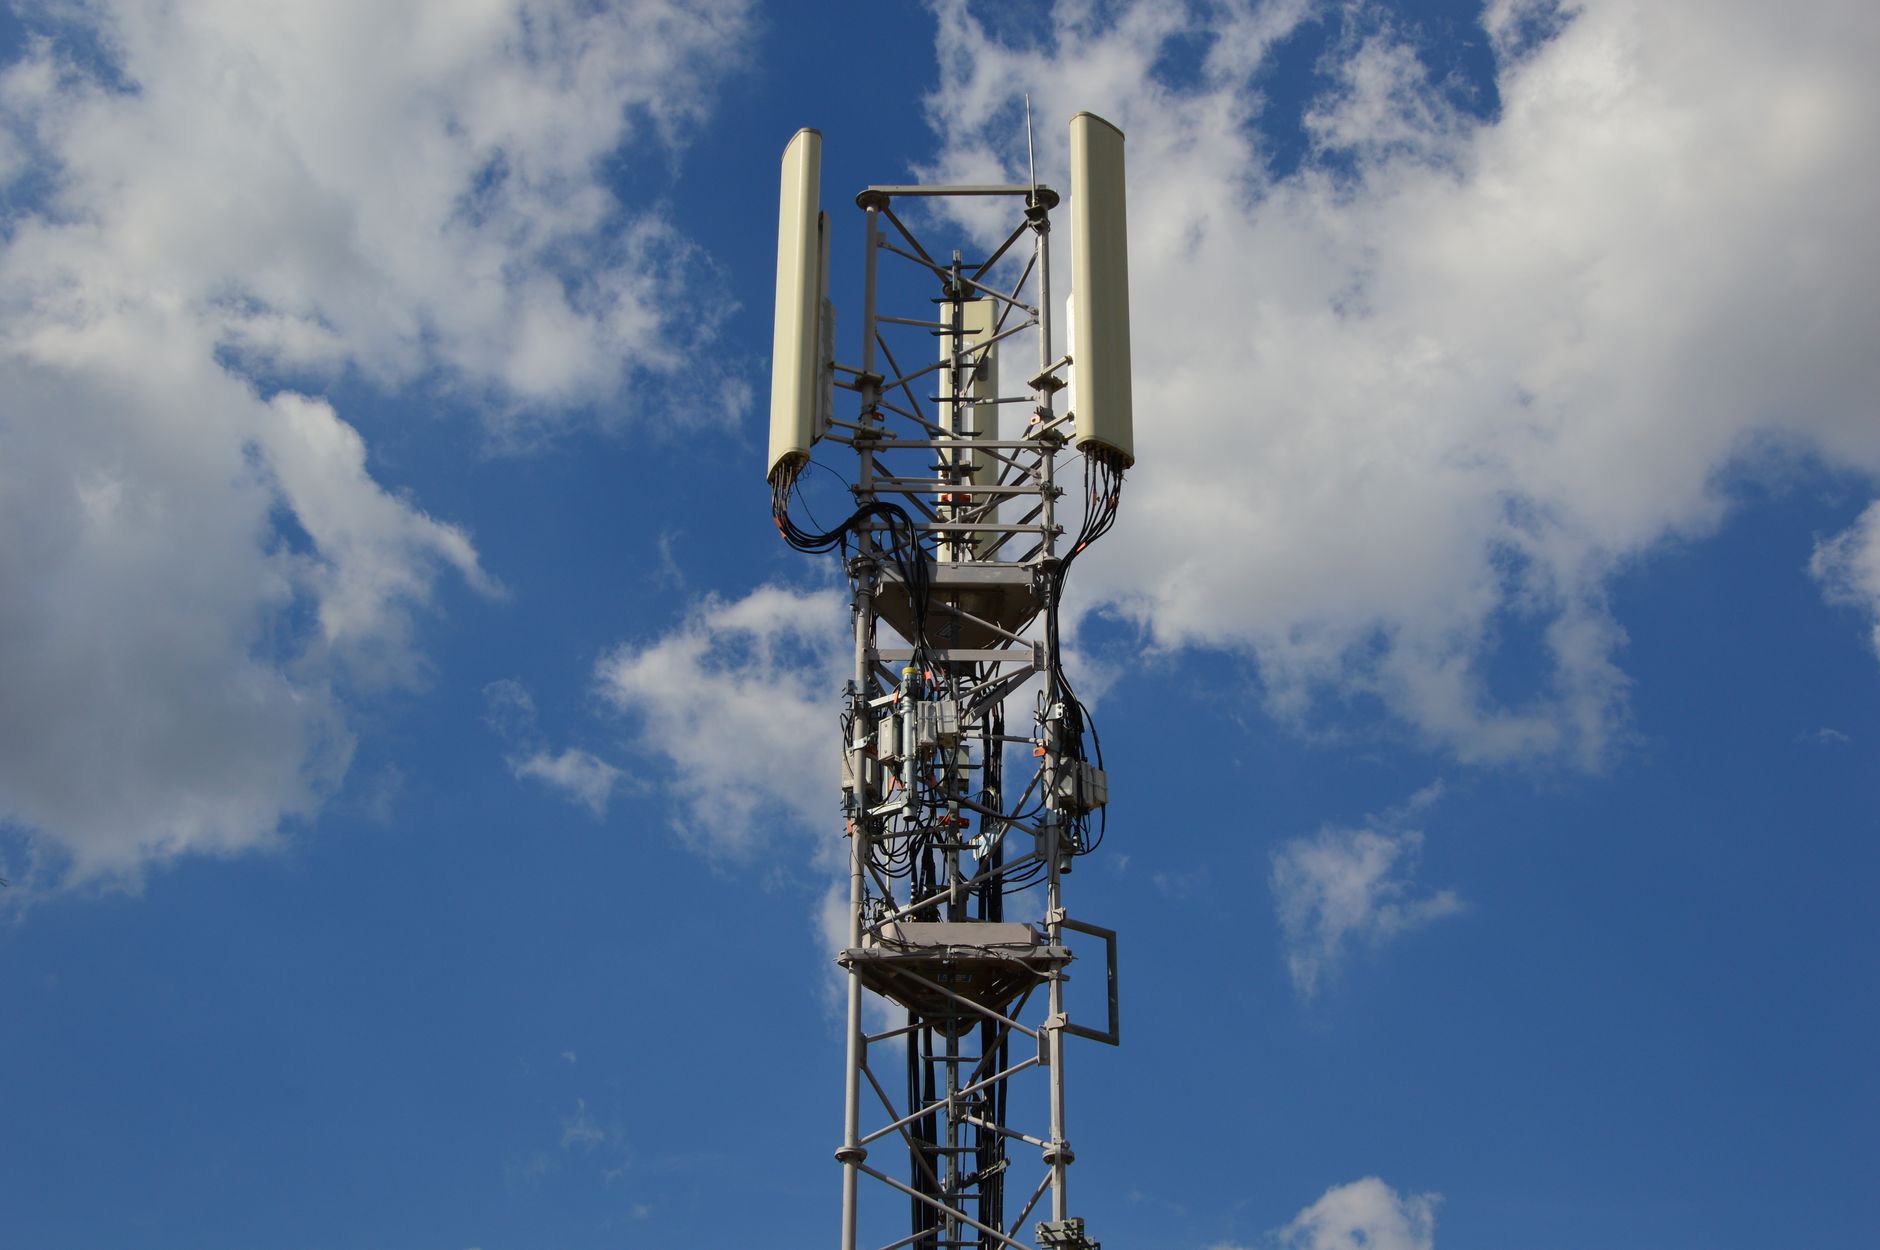
Photo by Ulrick Trappschuh on Pexels
The Business Case for AI in the RAN Is Materializing — Just Not Where Operators Expected
For years, the telecom industry has been promised that artificial intelligence would revolutionize the radio access network — unlocking new revenue streams, turbocharging network performance, and transforming how operators compete. The reality emerging from the front lines of deployment is more nuanced, and in many ways, more immediately practical: AI in the RAN is already generating a return on investment, but that payback is living squarely in network operations, not in demand generation.
That was the consensus signal coming out of recent Intelligent RAN Forum discussions, where a panel of industry experts acknowledged that while AI-RAN’s efficiency story is proving out in the field, the demand-side argument — the idea that AI-optimized networks will unlock new premium services customers will pay more for — remains largely theoretical for now.
Where the Money Is Actually Coming From
Energy Efficiency: The Clearest Win
Energy costs represent one of the largest operational expenditures for any mobile network operator. Base stations alone can account for 60 to 80 percent of a network’s total energy consumption, and with electricity prices volatile across global markets, squeezing efficiency out of radio hardware has become a financial imperative — not just a sustainability talking point.
AI-driven energy optimization tools are now demonstrably delivering on this front. Machine learning models that predict traffic load patterns and dynamically power down or scale back radio units during low-demand periods are showing measurable kilowatt-hour savings across large-scale deployments. Operators including Vodafone, Deutsche Telekom, and several Asian carriers have reported energy reductions in the range of 10 to 20 percent on targeted cell sites, with some AI-assisted sleep mode implementations pushing savings even higher during off-peak windows.
For an operator running tens of thousands of base stations, even a modest percentage reduction in energy consumption translates to millions of dollars in annual savings — making AI one of the fastest-payback technology investments available in the current capex environment.
Operational Automation and Self-Healing Networks
Beyond energy, AI is proving its value in automating the labor-intensive tasks that have long burdened network operations centers. Fault detection, root cause analysis, and automated remediation workflows are reducing mean-time-to-repair metrics and decreasing the volume of truck rolls required for routine interventions. AI models trained on historical performance data can now identify degradation patterns hours or even days before they become service-affecting events — shifting operators from reactive to genuinely predictive network management.
This operational efficiency layer also extends into radio resource management. AI-assisted interference mitigation, dynamic spectrum allocation, and load balancing between cells are optimizing spectral efficiency in ways that static, rule-based systems simply cannot match — particularly in dense urban environments where network conditions can shift dramatically within minutes.
The Demand-Side Gap: Why Revenue Growth Remains Elusive
Despite the operational wins, the more ambitious half of the AI-RAN value proposition — using network intelligence to create differentiated experiences that command premium pricing or enable new revenue streams — has yet to materialize at scale.
The challenge is partly a market readiness issue. Enterprise customers and consumers have not yet demonstrated consistent willingness to pay a premium specifically for AI-optimized connectivity experiences. Network slicing, which was expected to be a key vehicle for monetizing AI-driven quality differentiation, has had a slower commercial rollout than the industry anticipated. Most operators are still in early pilot phases with enterprise slice offerings, and retail 5G pricing remains stubbornly flat in most markets.
There’s also a fundamental attribution problem. When an AI system improves latency or reduces dropped calls in a specific area, quantifying how much of that improvement drives incremental revenue versus simply meeting baseline customer expectations is analytically difficult. The business case exists in theory; the accounting for it in practice remains a work in progress.
Open RAN’s Role in Scaling AI-RAN Deployments
The Open RAN architecture is increasingly being positioned as the enabling layer that will allow AI-RAN applications to scale beyond individual vendor ecosystems. By disaggregating hardware and software layers and exposing standardized interfaces — particularly the RAN Intelligent Controller (RIC) framework defined by the O-RAN Alliance — operators gain the flexibility to deploy third-party AI applications as xApps and rApps that can optimize network behavior in near-real-time and real-time loops.
This architectural openness is critical because it decouples AI innovation from the traditional vendor refresh cycle. Operators no longer need to wait for their primary RAN vendor to integrate an AI capability; they can source best-of-breed optimization applications and deploy them across a disaggregated infrastructure. Vendors like Ericsson, Nokia, and Samsung are all advancing their AI-native RAN roadmaps, while a growing ecosystem of specialist AI software companies — including firms like Cognizant’s network AI division, Amdocs, and startups like Cellwize (now part of Cisco) — are targeting the rApp and xApp opportunity.
Industry Outlook: Patience Required, But the Foundation Is Being Laid
The honest assessment from industry observers is that AI-RAN is in an early maturity phase that mirrors where cloud computing was roughly a decade ago: clear efficiency benefits are visible and bankable, while the transformative revenue upside is real but still largely ahead of the curve.
For operators under sustained pressure to justify 5G capital expenditure, the operational ROI story is not a consolation prize — it’s a genuine and defensible business case that is funding continued investment in AI capabilities. The expectation within the industry is that as AI models become more sophisticated, data pipelines more mature, and enterprise use cases more clearly defined, the demand-side equation will begin to close.
In the meantime, the operators building deep AI expertise into their network operations today are positioning themselves to move fastest when market conditions shift. The payback is real. The bigger payoff is simply still loading.
